Cash flow and working capital play a crucial role in the success of every business. Even companies with strong sales can face financial difficulties when customers delay payments or outstanding invoices remain unpaid for extended periods. These delays can affect supplier payments, inventory purchases, employee salaries, and everyday business operations.
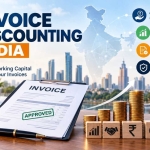
Invoice discounting provides a financing option that allows eligible businesses to access funds against unpaid customer invoices instead of waiting for the full payment period. In India, this approach can help businesses manage short-term cash flow gaps, maintain operational stability, and support growth.
Understanding how invoice discounting works, its benefits, eligibility requirements, and associated costs can help businesses make informed decisions about their financing needs.
What Is Invoice Discounting?
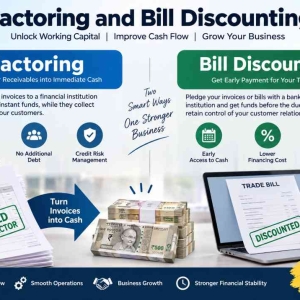
Invoice discounting is a short-term financing arrangement in which a business receives an advance against eligible unpaid invoices issued to its customers. Rather than waiting until the customer pays, the business can access a portion of the invoice value through a financing provider.
The customer generally pays according to the agreed credit terms, while the business meets its obligations under the financing agreement. Depending on the arrangement, the financing provider may collect payment directly or receive settlement through the business.
For example, a company issues an invoice worth Rs. 6 lakh to a customer with a payment term of 60 days. Instead of waiting two months, the company may receive an advance against the invoice if it qualifies for financing. The provider charges applicable interest or discount fees according to the agreement.
This can help the company cover operational expenses, pay suppliers, replenish inventory, and maintain sufficient working capital.
Invoice discounting differs from a traditional business loan because the financing is linked to eligible invoices or receivables. However, the advance amount, approval requirements, and repayment terms depend on the provider and the financing structure.
Why Cash Flow and Working Capital Matter
Working capital represents the funds a business uses to manage its short-term assets and liabilities. It helps companies purchase inventory, pay suppliers, cover wages, and meet other operating expenses.
When customers take longer to pay their invoices, businesses may experience a gap between money going out and money coming in. This situation can create challenges even when the company has a healthy order book.
Common working capital challenges include:
- Delayed customer payments and overdue invoices.
- Supplier payments that fall due before customer collections.
- Rising inventory and operating costs.
- Seasonal fluctuations in sales.
- Limited funds to fulfil larger orders.
- Unexpected expenses that put pressure on available cash.
Invoice discounting may help address these challenges by providing earlier access to funds tied up in eligible receivables.
How Does Invoice Discounting Work in India?
The process generally involves several steps.
1. Issue an Invoice to the Customer
The business supplies goods or services and issues an invoice with an agreed payment period. The invoice should represent a genuine transaction and satisfy the financing provider's requirements.
2. Apply for Invoice Discounting
The business approaches a bank, non-banking financial company, or eligible financing platform that offers invoice-based funding. It submits the invoice and the supporting documents requested by the provider.
3. Complete Invoice Verification
The provider reviews the invoice, supporting transaction records, customer details, and relevant financial information. Depending on the arrangement, it may also assess the creditworthiness of the customer and the business's repayment capacity.
4. Receive an Advance
Once the invoice is approved, the business receives an agreed portion of its value. The advance percentage, approval time, and funding limit depend on the provider's policies and the terms of the facility.
5. Customer Payment and Settlement
The customer pays according to the agreed payment terms. The financing is then settled according to the contract, including applicable charges.
Businesses should confirm how payments are collected and whether they remain responsible for unpaid invoices before accepting an offer.
How Invoice Discounting Improves Cash Flow
Invoice discounting can help businesses manage the timing difference between issuing invoices and receiving payments.
Faster Access to Funds
Instead of waiting until an invoice reaches its due date, a business may access funds earlier. This can help cover immediate expenses and reduce pressure on available cash.
More Predictable Financial Planning
Earlier access to receivables may make it easier to plan supplier payments, operating expenses, and inventory purchases. However, businesses should still account for financing costs and repayment obligations.
Fewer Operational Disruptions
A temporary shortage of working capital can interrupt production, delay orders, or affect supplier relationships. Suitable financing may help businesses maintain continuity while waiting for customer payments.
Better Management of Payment Cycles
Businesses often need to pay suppliers before receiving money from customers. Invoice discounting may help bridge this gap and create greater flexibility in managing payment schedules.
Greater Capacity to Handle Demand
When sales increase, businesses may need additional inventory, staff, transportation, or production resources. Access to funds against eligible invoices may help them meet these requirements.
Benefits of Invoice Discounting for Businesses in India
Invoice discounting can offer several advantages when used responsibly.
1. Improved Working Capital Availability
Businesses can access funds that would otherwise remain tied up in unpaid invoices. This can help them manage short-term liabilities and routine expenses.
2. Timely Supplier Payments
Having sufficient working capital can help businesses pay suppliers on schedule, maintain trust, and reduce the risk of supply interruptions.
3. Support for Business Expansion
Growing businesses may need more funds to fulfil larger orders or serve additional customers. Invoice discounting may help provide liquidity without requiring them to wait for existing receivables to be collected.
4. Reduced Pressure on Cash Reserves
Businesses may preserve some of their available funds for emergencies, unexpected costs, and strategic investments.
5. Flexible Financing Opportunities
Depending on the provider, a business may seek financing against selected eligible invoices rather than relying exclusively on a conventional loan. Availability and limits remain subject to approval.
6. Better Operational Efficiency
Access to working capital may help businesses manage payroll, logistics, raw materials, and other operational requirements more consistently.
7. Support for Small and Medium-Sized Enterprises
Small and medium-sized enterprises can face significant cash flow challenges when customers negotiate extended payment terms. Invoice discounting may provide a financing option for eligible businesses that need earlier access to their receivables.
Understanding Purchase Invoice Discounting
Purchase invoice discounting is a related term generally used for financing associated with supplier invoices or purchase transactions. Its precise meaning and structure depend on the provider and the financing product.
A business may require purchase-related financing to pay suppliers, acquire inventory, or manage the period between purchasing goods and receiving revenue.
For example, a manufacturer may need to buy raw materials to fulfil a customer order but may not have enough immediately available cash. A suitable purchase-related financing facility may help meet eligible supplier payment obligations, subject to approval and the agreement.
It is important to distinguish purchase invoice discounting from sales invoice discounting.
Sales invoice discounting involves obtaining an advance against unpaid invoices issued to customers. Purchase-related financing focuses on eligible supplier purchases or payment obligations.
The funding recipient, supporting documentation, repayment structure, and allocation of risk may differ. Businesses should verify the exact structure of the financing product before applying.
Invoice Discounting vs. Traditional Business Loans
Both invoice discounting and traditional business loans can help businesses access funds, but their structures and uses differ.
|
Feature |
Invoice Discounting |
Traditional Business Loan |
|
Financing basis |
Eligible invoices or receivables |
Credit assessment and loan terms |
|
Main purpose |
Improve liquidity tied up in unpaid invoices |
Finance working capital or broader business needs |
|
Funding amount |
Depends on invoice eligibility and provider limits |
Depends on the approved loan amount |
|
Repayment |
Based on the financing agreement |
Usually follows an agreed repayment schedule |
|
Documentation |
Invoices and supporting transaction records |
Financial statements and loan application documents |
|
Costs |
Interest, discount charges, and applicable fees |
Interest and applicable loan charges |
The right option depends on the business's cash flow cycle, funding requirements, financial position, and repayment capacity. Businesses should compare the total cost and terms before making a decision.
Who Can Benefit From Invoice Discounting in India?
Invoice discounting may be suitable for businesses that sell goods or services on credit and maintain eligible outstanding receivables.
Common examples include:
- Manufacturing companies: Businesses supplying finished goods to distributors and corporate customers.
- Wholesale and distribution businesses: Companies that sell inventory on credit and need funds to replenish stock.
- Small and medium-sized enterprises: Businesses experiencing cash flow gaps due to delayed customer payments.
- IT and professional service providers: Companies that invoice clients for completed projects and services.
- Logistics businesses: Service providers that incur operating expenses before collecting payments.
- Growing enterprises: Businesses that need working capital to fulfil larger orders and expand operations.
Eligibility depends on the provider's policies, invoice validity, customer payment history, financial records, and the business's ability to meet its obligations.
Documents Required for Invoice Discounting
Documentation requirements vary between financing providers. Businesses may be asked to provide:
- Business registration documents and applicable tax registrations.
- PAN and identity verification documents.
- Customer invoices and relevant purchase orders.
- Delivery challans, goods receipt notes, or service completion records.
- Bank statements and financial statements.
- GST returns and other relevant tax records.
- Customer information and payment history.
- Details of existing borrowings and financial obligations.
Providing accurate and complete documents can help reduce verification delays.
Costs and Charges Associated With Invoice Discounting
Before selecting an invoice discounting facility, businesses should understand its total cost.
Interest or Discount Fees
The financing provider may charge interest or a discount fee based on the amount advanced and the duration of the financing.
Processing Fees
Some providers charge fees for assessing and processing the application.
Platform or Transaction Charges
Additional charges may apply depending on the provider and transaction structure.
Late Payment Charges
The agreement may specify additional fees if the business fails to meet its repayment obligations on time.
Other Contractual Costs
Certain arrangements may include documentation charges, security-related expenses, or other applicable fees.
Businesses should request a clear breakdown of charges and compare the total financing cost rather than focusing only on the advertised rate.
Risks and Limitations of Invoice Discounting
Although invoice discounting can support working capital management, businesses should understand the associated risks.
Customer payment delays: A customer may pay late, while the business may still have repayment obligations.
Invoice disputes: Disputed, cancelled, or incorrectly documented invoices may not qualify for financing.
Financing costs: Repeated use of invoice discounting can reduce profitability if the cost outweighs the benefit of earlier access to funds.
Recourse obligations: Under recourse financing, the business may remain liable if the customer fails to pay. Non-recourse arrangements cover specified risks subject to contractual exclusions and conditions.
Funding limits: Providers may impose limits based on invoice values, customer concentration, industry, and financial risk.
Contractual requirements: Some facilities may require guarantees, security arrangements, assignment of receivables, or particular payment procedures.
Businesses should review the agreement carefully and assess whether expected cash inflows can support repayment.
How to Choose the Right Invoice Discounting Provider
Selecting the right financing provider requires comparing several factors.
Compare Total Financing Costs
Review interest, discount charges, processing fees, platform fees, and other applicable charges.
Check Eligibility Criteria
Confirm whether the provider supports the business's industry, invoice types, customer profiles, and transaction documentation.
Understand Funding Timelines
Ask how long invoice verification, approval, and disbursement generally take.
Review Repayment Terms
Understand the repayment schedule, payment collection process, and consequences of late payment.
Verify Provider Credentials
Check the provider's legal identity, applicable regulatory status, contractual documentation, and customer support.
Understand Recourse and Security Conditions
Determine who bears the risk of customer non-payment and whether collateral or guarantees are required.
Assess Financing Flexibility
Review advance limits, minimum invoice values, customer concentration restrictions, and requirements for repeat transactions.
A suitable provider should offer terms that align with the business's working capital needs and financial capabilities.
Best Practices for Improving Cash Flow and Working Capital
Invoice discounting works best when combined with effective financial management practices.
- Maintain accurate invoices and transaction records.
- Follow up on overdue customer payments.
- Negotiate appropriate credit terms with suppliers and customers.
- Forecast expected cash inflows and operating expenses.
- Borrow only what is required for genuine working capital needs.
- Compare financing costs with the expected benefit of receiving funds earlier.
- Monitor repayment dates and outstanding liabilities.
- Maintain contingency funds for unexpected expenses.
- Avoid relying on short-term financing to cover persistent operating losses.
These practices can help businesses maintain healthier cash flow and use financing more responsibly.
Conclusion
Invoice discounting in India can be a useful financing option for businesses seeking to improve cash flow and working capital management. By accessing funds against eligible unpaid customer invoices, businesses may be better positioned to pay suppliers, maintain inventory, cover operating expenses, and respond to growth opportunities.
Businesses considering purchase invoice discounting should understand how it differs from sales invoice discounting and confirm the exact structure of the financing facility. Comparing providers, assessing total costs, reviewing repayment conditions, and planning cash flows carefully are essential steps before borrowing.
When used responsibly, invoice-based financing can complement sound financial planning and help businesses maintain smoother operations while pursuing sustainable growth.
Frequently Asked Questions
1. What is invoice discounting in India?
Invoice discounting India is a financing arrangement that allows eligible businesses to receive an advance against unpaid customer invoices, subject to verification and approval.
2. How does invoice discounting improve cash flow?
It allows businesses to access funds earlier instead of waiting for customers to pay. The funds may help cover operating expenses, supplier payments, and inventory requirements.
3. Is invoice discounting suitable for small businesses?
It may be suitable for small businesses with genuine invoices, eligible customers, and temporary working capital needs. Approval depends on the financing provider's requirements and the business's financial position.
4. What is the difference between purchase invoice discounting and sales invoice discounting?
Purchase invoice financing generally supports eligible supplier purchases or payment obligations. Sales invoice discounting allows businesses to access funds against unpaid invoices issued to customers.
5. What costs are involved in invoice discounting?
Potential costs include interest or discount charges, processing fees, transaction fees, and other contractual charges. Businesses should review the complete cost before accepting an offer.
6. Does invoice discounting require collateral?
Requirements depend on the provider and financing structure. Some facilities may involve security, guarantees, or assignment of receivables, while others may follow different arrangements.
7. What should businesses check before applying?
Businesses should compare providers, verify eligibility, review all fees, understand repayment and recourse conditions, and confirm that expected cash flows are sufficient to meet financing obligations.